Fed Hike Repricing After Strong August Jobs Data Shifts
How strong US jobs data is reshaping Fed expectations and equity valuations
Accelerating job growth and sticky global price pressures have shifted market expectations away from policy easing toward additional tightening. Higher interest rate projections raise discount rates and compress valuations for long-duration growth stocks. At the same time, the economic strength behind those higher rates supports corporate earnings, cushioning broader market drawdowns.
The policy shift: from patience to potential hikes
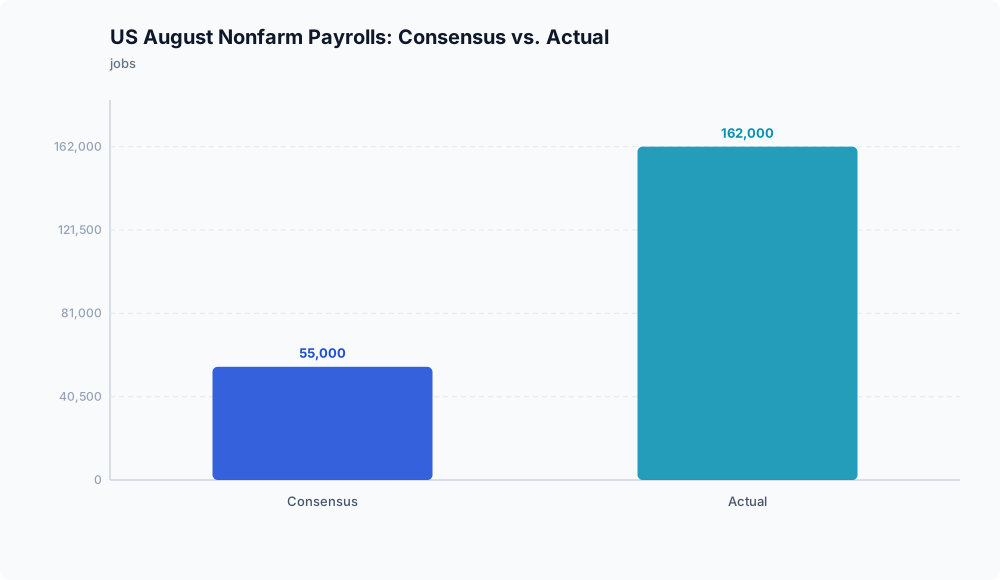
The shift in the macroeconomic outlook follows a sharp upside surprise in the US labor market. In August 2026, US nonfarm payrolls expanded by 162,000, nearly triple the consensus estimate of 55,000, according to UBS. That increase showed that labor demand remained firm, challenging assumptions that earlier monetary tightening had sufficiently slowed domestic economic activity.
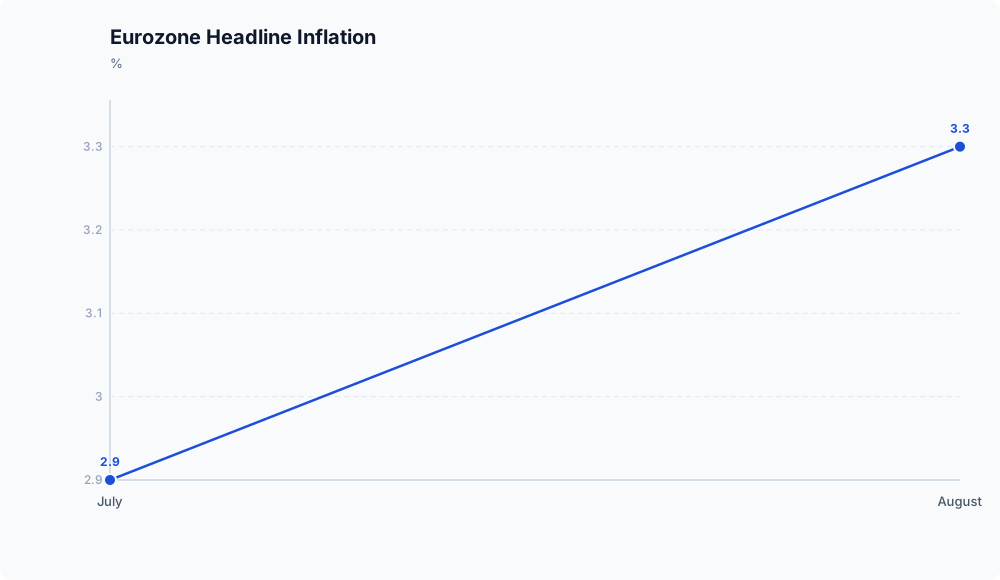
International price pressures have also picked up. In the Eurozone, headline inflation climbed to 3.3% in August from 2.9% in July, as reported by UBS.
Together, persistent inflation and a tight labor market reduce the immediate pressure on central banks to cut rates to support employment. In response, UBS adjusted its baseline forecast to project two 25-basis-point interest rate increases from the Federal Reserve in 2026. Under this revised outlook, the Fed is viewed as likely to raise rates unless upcoming inflation reports confirm that disinflation remains on track. Because this forecast reflects a private financial institution’s projections rather than official guidance, future policy remains dependent on upcoming consumer and producer price data.
The equity impact: valuation compression vs. resilient cash flows
Strong employment figures create conflicting pressures for equities.
Higher interest rate expectations present a headwind for growth stocks trading at elevated multiples. Long-duration assets derive much of their estimated value from projected cash flows far into the future. As sovereign yields and benchmark rates climb, the discount rate applied to those distant earnings rises, reducing present valuations even when underlying business operations remain sound.
Tightening driven by economic growth, however, differs from tightening during late-cycle stagflation. Stronger consumer and business demand can support corporate revenues, offsetting valuation pressure through operational performance. For example, Broadcom recently raised its projected AI-chip revenue for the fiscal year ending October 2027 to approximately USD 115 billion, up from an earlier forecast exceeding USD 100 billion, according to UBS.
Market implications
The latest data shows that monetary policy uncertainty remains active across developed economies. With markets pricing in potential Federal Reserve rate hikes, investors can no longer count on multiple expansion to drive equity returns. Portfolio performance will depend more directly on whether corporate earnings growth can outpace higher hurdle rates.
Disclaimer: This analysis is for informational purposes only and does not constitute investment, financial, real estate, or legal advice. Always consult a licensed financial advisor before making investment decisions.