Treasury Yield Surge: Real Estate Valuation & 2026 Gridlock
Treasury yield surges and real estate valuations: understanding the 2026 transaction gridlock
Why did commercial real estate transactions stall in the first half of 2026 even though property capitalization rates remained flat?
Commercial real estate deal flow froze because surging sovereign bond yields increased borrowing costs and reduced the real estate risk premium, while property owners resisted discounting their assets. When benchmark yields rise without an expansion in capitalization rates, prospective buyers must lower their bids to hit required returns. Sellers, however, remain anchored to prior peak pricing. This gap widened the bid-ask spread and restricted market liquidity throughout the first six months of the year.
The divergence between bond yields and cap rates
When sovereign yields climb, debt financing costs and return hurdles rise immediately for prospective buyers. If property yields do not adjust upward to compensate for these higher capital costs, transaction volume drops.
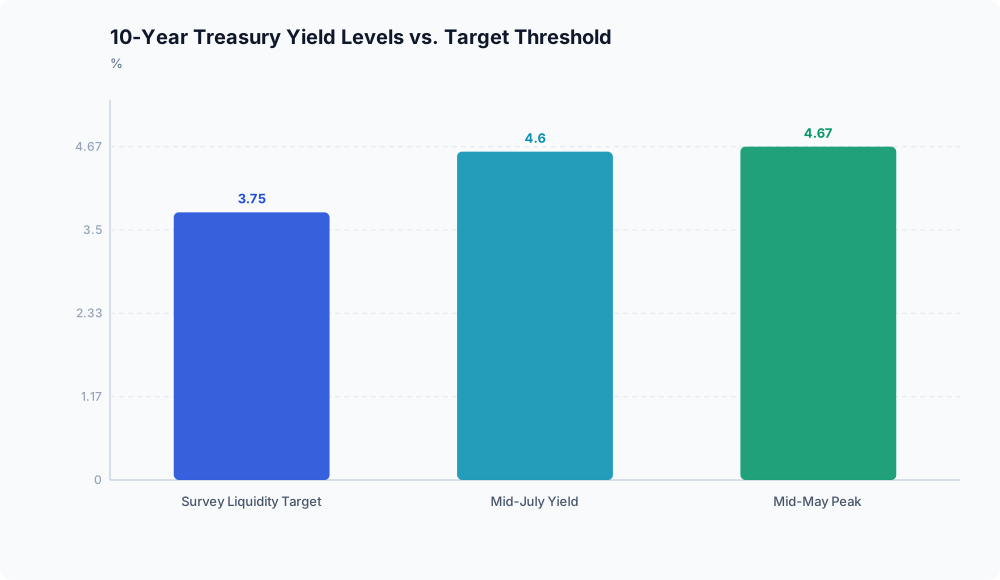
This dynamic affected the U.S. commercial property market during the first half of 2026. According to the CBRE U.S. Cap Rate Survey H1 2026, the 10-year U.S. Treasury yield briefly dipped below 4% in late February before surging to peak at 4.67% in mid-May. It continued to hover near 4.6% into mid-July.
Despite this benchmark run-up and sustained rate volatility, the all-property average cap rate held essentially flat across the United States over the same period, as reported by CBRE. Because cap rates did not drift upward alongside benchmark debt costs, the spread between property yields and risk-free Treasuries compressed, leaving buyers unable to justify purchase prices at prevailing interest rates.
The 3.75% liquidity threshold
Market participants largely expect interest rate relief to restore activity instead of property price cuts. Commercial real estate professionals surveyed by CBRE identified a median target of 3.75% for the 10-year Treasury yield as the specific trigger required to revive sales activity.
With prevailing yields hovering near 4.6% as of mid-July—roughly 85 basis points above the 3.75% benchmark identified by CBRE—the cost of debt capital remains too restrictive for widespread transactions. Sellers see little motivation to accept discounts while waiting for potential rate cuts, while buyers cannot make underwriting models work at current borrowing rates without price reductions.
Analytical outlook: yield spreads and market pressures
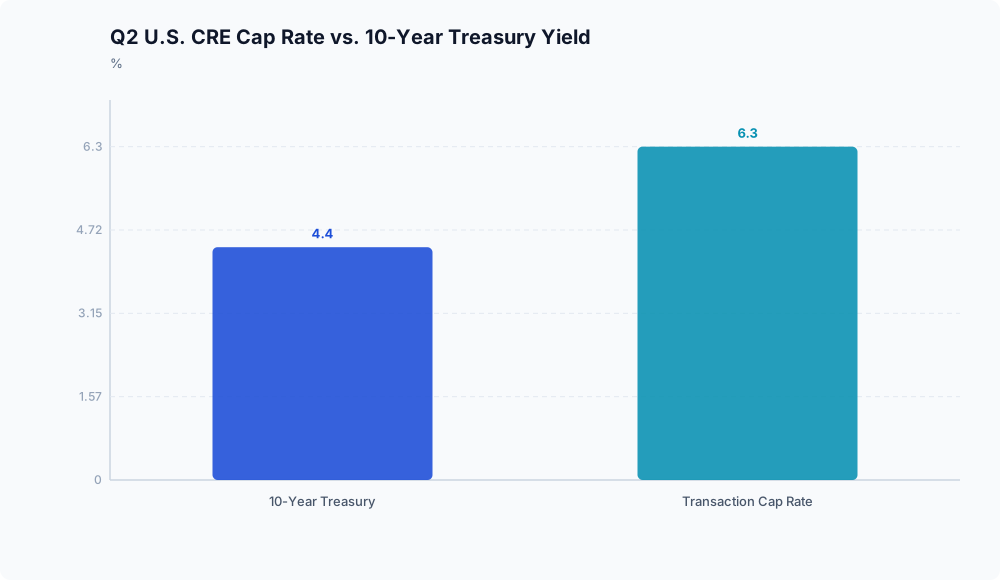
In the second quarter of 2026, transaction-based U.S. commercial real estate cap rates averaged approximately 6.3% while the 10-year Treasury averaged about 4.4%, according to First American data cited by The CRE Report.
The persistence of the gap between prevailing yields near 4.6% and the 3.75% market liquidity threshold reported by CBRE keeps financing conditions tight and transaction spreads compressed.
Resolution will require one of two outcomes: benchmark Treasury yields must retreat toward the 3.75% threshold, or sellers must eventually accept wider cap rates and reset asset valuations downward to clear the market.
Disclaimer: This analysis is for informational purposes only and does not constitute investment, financial, real estate, or legal advice. Always consult a licensed financial advisor before making investment decisions.
Frequently asked questions
Why did all-property cap rates remain flat in H1 2026 despite the rise in Treasury yields?
Cap rates remained essentially flat because property sellers remained anchored to earlier valuations and resisted discounting their assets, according to data from CBRE. Because asset prices did not drop to match higher borrowing costs, transaction volumes stalled as buyers and sellers reached an impasse.
Why do market participants target a 3.75% Treasury yield to resume sales activity?
According to the CBRE U.S. Cap Rate Survey H1 2026, a 3.75% 10-year Treasury yield represents the median threshold where debt financing becomes affordable enough to restore an adequate real estate risk premium without requiring sellers to reduce property values.